
Most people learn how to choose a health plan the hard way: they pick the one with the lowest monthly premium, then get a bill they never saw coming. The premium is only one of four numbers that decide what a plan really costs you. In many cases it isn’t even the biggest one.
Open enrollment is here. On HealthCare.gov it runs from 1 November to 15 January, and most workplace windows close in November. Meanwhile, costs are climbing. KFF’s latest employer survey found workers now pay $7,471 a year toward family coverage, up 9% in a year. And the legal cap on what a plan can make you pay in a year jumps to $12,000 for one person.
So this guide gives you a simple method we call the bad year test, a free Health Plan Chooser that does the math for up to three plans, and three worked examples. You’ll know which plan is actually cheapest for you in about ten minutes.
Quick answer
- Never choose a health plan by premium alone. Your real yearly cost is premiums plus what you pay for care, minus any employer HSA money and tax savings.
- Run the bad year test. Add a year of premiums to the out-of-pocket maximum. That’s the most the plan can cost you in a terrible year. Then pick the plan that is cheapest in a normal year and still survivable in a bad one.
- For healthy people, an HDHP with an HSA usually wins, especially when your employer adds money to the HSA. In our single-person example, it costs $1,506 in a normal year against $2,900 for the PPO.
- A PPO or HMO with low copays wins when you use a lot of care and the premium gap is small. In our chronic-condition example, the PPO saves $394 in a normal year and $2,141 in a bad one.
- HMO vs PPO is mostly about doctors, not money. An HMO is usually cheaper but limits you to its network and needs referrals. A PPO costs more for freedom to see anyone.
Latest data: health plan costs and limits (checked 31 October 2026)
| What | Latest figure | Source |
|---|---|---|
| Marketplace open enrollment | 1 Nov to 15 Jan on HealthCare.gov; enroll by 15 Dec for coverage from 1 Jan. State marketplaces can have different dates | HealthCare.gov |
| Average employer premium, single | $9,804 a year, of which workers pay $1,672 | KFF Employer Health Benefits Survey 2026 |
| Average employer premium, family | $28,303 a year, of which workers pay $7,471 (up 9%) | KFF 2026 |
| Average deductible, single coverage | $1,955; 38% of workers have $2,000 or more | KFF 2026 |
| Which plans workers have | PPO 50%, HSA-qualified 29%, HMO 12%, POS 8% | KFF 2026 |
| Out-of-pocket maximum cap, next plan year | $12,000 single, $24,000 family (was $10,600 and $21,200) | CMS |
| HSA-qualified plan limits, next year | Minimum deductible $1,750 single, $3,500 family; out-of-pocket cap $8,700 and $17,400 | IRS Rev. Proc. 2026-24 |
| HSA contribution limit, next year | $4,500 single, $9,000 family, plus $1,000 if 55 or older | IRS Rev. Proc. 2026-24 |
| Marketplace premiums | Insurers proposed a median 14% rise for next year; enhanced tax credits ended after 2025 | KFF |
We update this box each year when the IRS, CMS and KFF publish new numbers.
How to Choose a Health Plan in 5 Steps
Here’s how to choose a health plan in one list. The rest of this guide explains each step.
- List your must-haves. Write down your doctors, your regular prescriptions and any planned care, such as a baby, a surgery or therapy.
- Check the network and drug list first. Cross off any plan that doesn’t include your key doctors or covers your medicine at a high tier.
- Note four numbers for each plan that’s left: monthly premium, deductible, coinsurance or copays, and out-of-pocket maximum.
- Run the bad year test. Work out the real yearly cost in a light, normal and bad year. Our Health Plan Chooser below does this for you.
- Choose the plan that’s cheapest in your likely year and that you could survive in a bad one. If you pick an HSA plan, set up your HSA payroll contribution on the same day.
HMO vs PPO vs EPO vs HDHP: What Each Plan Type Means
Before you choose a health plan, it helps to know what the letters mean. They describe two different things. HMO, PPO, EPO and POS describe the network: which doctors you can see and how. An HDHP describes the cost-sharing: a higher deductible in exchange for a lower premium. So an HDHP can also be a PPO or an HMO.
| Plan type | Network | Referral to see a specialist? | Out-of-network care | Premium | Best for |
|---|---|---|---|---|---|
| HMO (health maintenance organization) | Must use the plan’s doctors | Usually yes | Not covered, except emergencies | Usually lowest | People happy with one doctor group who want low, predictable costs |
| PPO (preferred provider organization) | Large network plus outside doctors | No | Covered, but you pay more | Usually highest | People who want to choose any specialist or see doctors in several states |
| EPO (exclusive provider organization) | Must use the plan’s doctors | No | Not covered, except emergencies | Middle | People who want no referrals but can stay in network |
| POS (point of service) | HMO-style network with some outside cover | Usually yes | Covered at a higher cost | Middle | People who want HMO prices with an escape hatch |
| HDHP (high-deductible health plan) | Any of the above | Depends on the network type | Depends on the network type | Low | Healthy people and savers who can open an HSA |
The HealthCare.gov glossary has a plain-English page on each of these health insurance plan and network types. Still, the network question is quick to answer. If your doctors are in a plan’s network, keep it on your list. If not, cross it off, whatever it costs.
The 4 Numbers to Check When You Choose a Health Plan
Every plan must give you a Summary of Benefits and Coverage, a standard document that makes plans easy to compare side by side. Find these four numbers on it before you choose a health plan.
1. Premium
This is what you pay each month just to have coverage, whether you see a doctor or not. On a workplace plan, use your share, which comes out of your paycheck. Multiply by 12 to get the yearly amount.
2. Deductible
This is what you pay for covered care each year before the plan starts sharing the cost. Free preventive care, such as a yearly checkup and most screenings, doesn’t count, because you pay nothing for it on any plan.
3. Coinsurance and copays
After the deductible, you usually pay a share of each bill, often 20%. That’s coinsurance. Many HMO and PPO plans also charge a flat copay, such as $30 for a doctor visit, and some let you pay that copay even before you meet the deductible. That detail matters a lot if you see a doctor often.
4. Out-of-pocket maximum
This is the most you can pay for covered, in-network care in a year. After you hit it, the plan pays 100%. Federal rules cap it at $12,000 for one person and $24,000 for a family next year. Plans that qualify for an HSA have a lower cap of $8,700 and $17,400. Your plan’s own limit is often well below these caps, so check it.
HealthCare.gov’s glossary explains exactly what counts toward the limit. Premiums never do, and nor does out-of-network care on most plans.
The Bad Year Test: How to Choose a Health Plan by Real Cost
Here’s the core of our method. For each plan, work out your real yearly cost like this:
Real yearly cost = premiums for 12 months + what you pay for care − employer HSA or HRA money − tax saved through an HSA
Then do it three times:
- Light year: a checkup and a couple of doctor visits.
- Normal year: a few visits plus one surprise, such as urgent care, a scan or physical therapy.
- Bad year: something big, such as a surgery, a hospital stay or a new baby. In a bad year you hit the out-of-pocket maximum, so the cost is simply premiums plus the out-of-pocket max, minus any HSA money and tax savings.
The bad year number is the most a plan can cost you in a year for in-network care. That makes it the fairest way to compare risk. A plan with a $50 lower premium but a $4,000 higher out-of-pocket maximum might look cheaper, yet it can cost you far more in the year you need it most.
So the rule is simple. Choose the health plan that is cheapest in the year you expect, as long as you could afford its bad year. If you can’t cover the bad year from savings, pick a plan with a lower out-of-pocket maximum, even if it costs a little more.
Health Plan Chooser: Compare Your Plans in 2 Minutes
To choose a health plan with the chooser below, use the numbers from your own plan summaries. It starts with example plans, so you can see how it works before you type anything. Switch to “Me plus family” for family examples.
Did the cheapest-looking plan win? For many people it doesn’t. The three examples below show why, and when the answer flips.
How to Choose a Health Plan: 3 Real Examples
These examples show how to choose a health plan using the same plans as the chooser, with a 22% federal tax bracket and 5% state tax. They’re realistic employer plans, but your own numbers will differ, so run yours too.
Example 1: Single and healthy, choosing between three workplace plans
Alex is 29, healthy, and has three options at work:
| PPO | HDHP with HSA | HMO | |
|---|---|---|---|
| Monthly premium (Alex’s share) | $140 | $55 | $95 |
| Deductible | $1,000 | $2,000 | $1,500 |
| Doctor visit before deductible | $30 copay | Counts toward deductible | $25 copay |
| Out-of-pocket maximum | $4,500 | $5,000 | $5,500 |
| Employer HSA money | None | $750 | None |
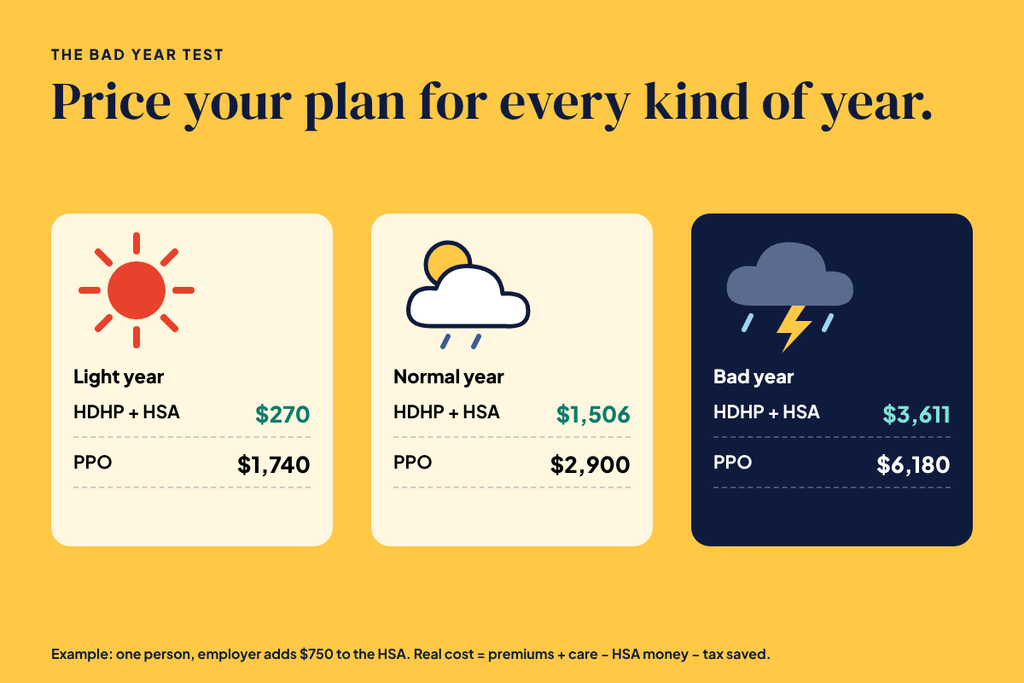
| Real cost, light year | $1,740 | $270 | $1,190 |
| Real cost, normal year | $2,900 | $1,506 | $2,740 |
| Real cost, bad year | $6,180 | $3,611 | $6,640 |
The HDHP wins in every year, even the bad one. That’s because its premium is $1,020 a year lower than the PPO’s, the employer adds $750 to the HSA, and paying bills from the HSA saves Alex about 35% in tax. Together, those cover most of the higher deductible.
There’s one catch. In a bad year, Alex has to pay up to $5,000 before the plan pays in full. So Alex needs that much in savings or in the HSA. If not, the safer way to choose a health plan here is the PPO, with its lower out-of-pocket maximum.
Example 2: A family of four
The Garcias have two young kids and expect around ten doctor visits a year:
| PPO | HDHP with HSA | HMO | |
|---|---|---|---|
| Monthly premium (family share) | $520 | $300 | $420 |
| Deductible | $2,000 | $4,000 | $3,000 |
| Out-of-pocket maximum | $9,000 | $10,000 | $11,000 |
| Employer HSA money | None | $1,500 | None |
| Real cost, light year | $6,420 | $3,180 | $5,190 |
| Real cost, normal year | $8,740 | $5,338 | $8,290 |
| Real cost, bad year | $15,240 | $9,501 | $16,040 |
Again, the HDHP comes out ahead. Choosing the PPO would cost the family about $3,400 more in a normal year. Over five years that’s roughly $17,000, which is enough to fill an emergency fund.
Example 3: When the PPO wins
Sam has a chronic condition with 12 specialist visits a year and regular tests. Sam’s employer offers only two plans and puts nothing into an HSA:
| PPO | HDHP with HSA | |
|---|---|---|
| Monthly premium | $110 | $85 |
| Deductible | $500 | $3,000 |
| Specialist visit | $40 copay | Counts toward deductible |
| Out-of-pocket maximum | $3,000 | $7,000 |
| Real cost, normal year | $3,000 | $3,394 |
| Real cost, bad year | $4,320 | $6,461 |
Here the PPO wins every year. The premium gap is only $300 a year, there’s no employer HSA money, and the out-of-pocket maximum is $4,000 lower. When you choose a health plan knowing you’ll use a lot of care, a low out-of-pocket maximum is worth more than a low premium.
Is an HDHP With an HSA Worth It?
For most healthy people, yes. A health savings account is the only account in the US tax code with a triple tax break. Money goes in tax free, grows tax free, and comes out tax free for medical costs. If it goes in through payroll, it also skips the 7.65% Social Security and Medicare tax. You keep the account even if you change jobs, and the money rolls over every year.
The IRS explains the rules in Publication 969. Next year you can put in up to $4,500 for yourself or $9,000 for a family, plus $1,000 if you’re 55 or older. That’s under Rev. Proc. 2026-24.
Choose a health plan with an HSA when:
- You’re fairly healthy and expect a light or normal year.
- Your employer puts money in the HSA. That’s free money you only get by choosing the HSA plan.
- The premium gap between plans is large, often $70 a month or more for one person.
- You have savings to cover the deductible if something happens.
It usually loses when:
- You use a lot of care, take expensive brand-name drugs, or expect a baby or surgery and the other plan has a much lower out-of-pocket maximum.
- Your employer adds nothing to the HSA and the premium gap is small.
- You don’t have the cash to pay the deductible. In that case, people tend to skip care they need, which costs more later.
There’s also a long-term bonus. After age 65 you can take HSA money out for anything, paying only normal income tax, just like a retirement account. So if you can afford to pay small bills from your pocket and leave the HSA invested, it becomes a second retirement fund.
Two rules changed recently. Since 1 January 2026, bronze and catastrophic plans count as HSA-eligible, according to IRS guidance under the new tax law. In addition, telehealth before the deductible no longer stops you from contributing.
Bronze, Silver or Gold: How to Choose a Health Plan on the Marketplace
If you buy your own insurance through HealthCare.gov or your state’s marketplace, plans come in metal tiers. The tier tells you how costs are split, not the quality of care. HealthCare.gov explains the health plan categories in more detail.
| Tier | Plan pays, on average | You pay, on average | Premium | Good for |
|---|---|---|---|---|
| Bronze | 60% | 40% | Lowest | Healthy people who mainly want protection from a big bill; now HSA-eligible |
| Silver | 70% | 30% | Middle | Anyone who qualifies for cost-sharing reductions (see below) |
| Gold | 80% | 20% | Higher | People who use a lot of care |
| Platinum | 90% | 10% | Highest | Heavy users, where offered |
| Catastrophic | Very little until a high deductible | Most costs until then | Very low | Under 30, or people with a hardship exemption |
The most important marketplace rule is about silver plans. If your income is up to 250% of the federal poverty level, you can get cost-sharing reductions, but only on a silver plan. They cut your deductible and out-of-pocket maximum, sometimes making a silver plan work like a gold or platinum one. So if your income is modest, check silver first when you choose a health plan.
Also, premiums are rising again. The enhanced tax credits ended after 2025, and KFF found insurers asked for a median 14% increase for next year. Don’t let last year’s plan renew automatically. Log in, update your income and choose a health plan again with fresh numbers.
Open Enrollment Checklist Before You Choose a Health Plan
Use this list before you choose a health plan for next year:
- Read your plan change notice. Your current plan may have new premiums, a new deductible or dropped doctors.
- Search each plan’s directory for your doctors, hospital and nearest urgent care. Call the office to confirm, because directories can be out of date.
- Look up your drugs in each plan’s formulary (drug list) and note the tier. A drug on a high tier can cost more than the premium gap.
- Add up last year’s medical spending from your insurer’s website. It’s the best guess for next year.
- Plan for known events, such as a baby, surgery, braces or a new diagnosis.
- Compare both spouses’ workplace plans, including any spousal surcharge.
- Decide on an HSA or FSA amount and set it in payroll during enrollment.
- Note your deadline. For HealthCare.gov, it’s 15 December for coverage from 1 January and 15 January at the latest. Workplace deadlines are often earlier, so check with HR.
How to Choose a Health Plan in Special Cases
Self-employed or freelancing
You’ll usually choose a health plan on the marketplace, and you may be able to deduct your premiums. Health insurance is often the biggest hidden cost of working for yourself, so build it into your rates. Our guide to one-person business expenses shows how. A bronze HSA plan can work well here, because HSA contributions cut your income tax.
Thinking about leaving your job
If you leave, you can usually keep your work plan through COBRA for up to 18 months, but you’ll pay the full premium plus up to 2%. That’s often $800 a month or more for one person. Losing work coverage also opens a 60-day special enrollment period on the marketplace, where you may qualify for help. Factor this in if you’re asking should I quit my job.
Under 26
You can stay on a parent’s plan until age 26, even if you’re married, live elsewhere or have your own job offer. Before you choose a health plan of your own, compare the two in the chooser. A parent’s plan may have a much higher family deductible.
Turning 65
Stop putting money into an HSA about six months before you sign up for Medicare. Medicare Part A coverage can start up to six months back, and you can’t contribute while on Medicare.
Common Mistakes When You Choose a Health Plan
These are the mistakes we see most often when people choose a health plan.
- Choosing by premium alone. It’s the most common mistake, and the examples above show it can cost thousands.
- Ignoring the out-of-pocket maximum. It’s your worst case, so it matters more than the deductible.
- Letting your plan renew without looking. Premiums, networks and drug lists change every year.
- Choosing an HDHP and not opening the HSA. Without the HSA and the tax break, much of the advantage disappears.
- Choosing a plan your doctor isn’t in. Out-of-network bills usually don’t count toward your out-of-pocket maximum.
- Forgetting your employer’s HSA money. It’s part of your pay. Leaving it on the table is like turning down a raise.
What to Read Next
How you choose a health plan changes your real pay. Our real hourly wage calculator shows what you earn once you count your premium and commute. If a job offer comes with better benefits, use those numbers when you negotiate a raise.
If your premium just went up, look for money elsewhere. Our guide to how much you spend on subscriptions helps you find some fast. And if you need extra income for a higher deductible, see which side hustles actually pay.
Open enrollment also falls right before the holidays. So set a realistic budget with our guide to how much to spend on Christmas, and buy anything big at the best time of year.
Finally, use your plan for your mind as well as your body. Most plans cover therapy, and a quick daily mental health check-in can tell you when it’s time. Understanding insurance is also one of the things you wish you learned in school, so share this with someone choosing their first plan.
Frequently Asked Questions About How to Choose a Health Plan
How do I choose a health plan?
First, cross off plans that don’t include your doctors and drugs. Then compare the rest by real yearly cost: premiums plus what you’d pay for care, minus employer HSA money and tax savings. Choose the plan that’s cheapest in a normal year and that you could afford in a bad one.
Is an HMO or PPO better?
Neither is better for everyone. An HMO usually costs less but limits you to its network and often needs referrals. A PPO costs more but lets you see specialists without referrals and covers out-of-network care. If your doctors are in the HMO network, the HMO is usually the better deal.
Is a high-deductible health plan worth it?
Usually, if you’re fairly healthy, your employer adds money to an HSA, and you have savings to cover the deductible. It’s often not worth it if you use a lot of care and another plan has a much lower out-of-pocket maximum.
What matters more, the deductible or the out-of-pocket maximum?
The out-of-pocket maximum, because it’s the most you can pay in a year for in-network care. The deductible only tells you when the plan starts sharing costs. Compare plans on premiums plus out-of-pocket maximum to see your worst case.
When is open enrollment?
On HealthCare.gov, open enrollment runs from 1 November to 15 January. Sign up by 15 December for coverage from 1 January. State marketplaces can have different dates. Workplace open enrollment dates are set by each employer, usually in October or November.
Should I choose bronze or silver?
Choose silver first if your income is up to 250% of the federal poverty level, because only silver plans get cost-sharing reductions. Otherwise, bronze often suits healthy people who want low premiums and an HSA, while silver or gold suits people who expect to use care.
Can I change my health plan after open enrollment?
Only if you have a qualifying life event, such as losing other coverage, moving, getting married or having a baby. These usually give you a 60-day special enrollment period. Otherwise you’ll keep your plan until the next open enrollment.
Sources
- HealthCare.gov, Health insurance plan and network types, Health plan categories, Out-of-pocket maximum and Cost-sharing reductions
- KFF, 2026 Employer Health Benefits Survey (more than 1,900 employers, released 22 October 2026)
- KFF, Preliminary marketplace rate filings (July 2026)
- Internal Revenue Service, Rev. Proc. 2026-24 (HSA and HDHP limits) and Publication 969
- Internal Revenue Service, Guidance on new HSA tax benefits (Notice 2026-5)
- Centers for Medicare and Medicaid Services, premium adjustment percentage and maximum out-of-pocket limits guidance (29 January 2026)
Join the Lifoholic community conversation. We welcome thoughtful insights, questions, and authentic experiences from our readers.
RECOMMENDED DISCUSSIONS
How to Stop Overthinking at Night: 9 Things That Actually Help
Am I Burned Out or Just Bored? A 2-Minute Self-Test (and What to Do Next)